


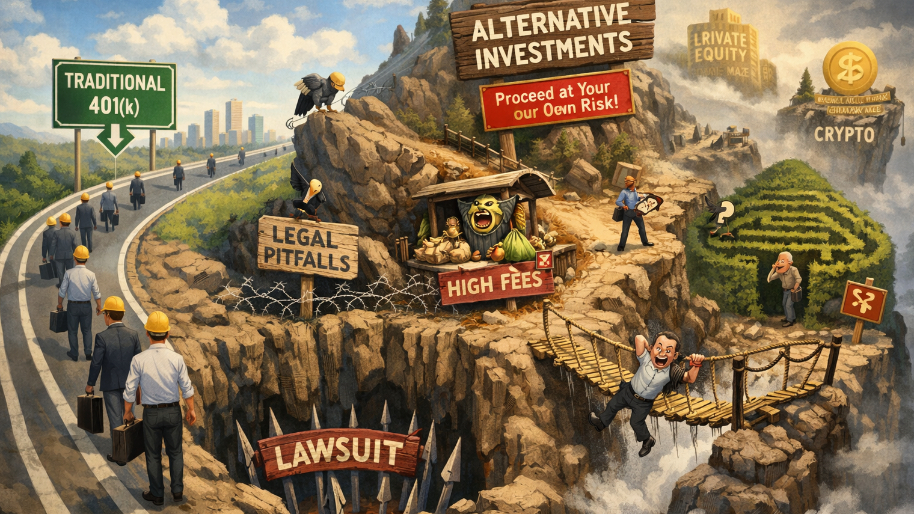
On Monday, the Labor Department proposed a new rule that could make it easier for 401(k) plans to include alternative assets… everything from private equity and private credit to real estate and crypto.
The move follows an executive order from Donald Trump last summer pushing regulators to open the door wider to these types of investments inside retirement accounts.
At the center of the proposal is a “safe harbor” framework. Put simply, it gives plan sponsors clearer guidelines (and some legal cover) when deciding whether to include alternative assets. That matters, because while 401(k)s were never explicitly barred from offering alts, most employers avoided them anyway due to the risk of getting sued if something went wrong.
The new rule tries to change that by laying out six things fiduciaries need to evaluate: performance, fees, liquidity, valuation, benchmarks, and complexity.
Supporters of this proposal argue that adding alternatives could help diversify portfolios and potentially improve long-term returns, especially as private markets have grown and institutional investors have shifted more capital in that direction.
But there’s a gap between what’s theoretically possible and what actually shows up in someone’s 401(k).
Even if this rule is finalized, most experts don’t expect a sudden wave of private equity or crypto funds appearing next to your S&P 500 index option. In reality, exposure would likely come through more controlled structures… like target-date funds that allocate a small slice to alternatives.
There are a few reasons for that.
First, these assets are harder to work with. They’re less liquid, more complex, and often come with higher fees. That creates challenges for plans that need to offer daily pricing and easy access for participants.
Second, the legal risk doesn’t disappear overnight. While the safe harbor helps, some analysts think plan sponsors will wait to see how courts interpret the rule before making any major changes. That could slow adoption meaningfully.
And then there’s the investor side.
Not everyone is convinced this is a net positive for the average 401(k) participant. Traditional low-cost index funds still do a pretty good job for most investors, and they’re easy to understand. Alternatives, on the other hand, are more vague… and in many cases, retail investors won’t have access to the top-tier funds anyway.
So while the proposal expands what retirement portfolios could include over time, it doesn’t materially change what they look like today.
At the time of publishing this article, Stocks.News doesn’t hold positions in companies mentioned in the article.
Did you find this insightful?
Bad
Just Okay
Amazing
Disclaimer: Information provided is for informational purposes only, not investment advice. We do not recommend buying or selling stocks. Stock price discussions are based on publicly available data. Readers should conduct their own research or consult a financial advisor before investing. Owners of this site have current positions in stocks mentioned throughout the site, Please Read Full Disclaimer for details Here https://app.stocks.news/page/disclaimer