


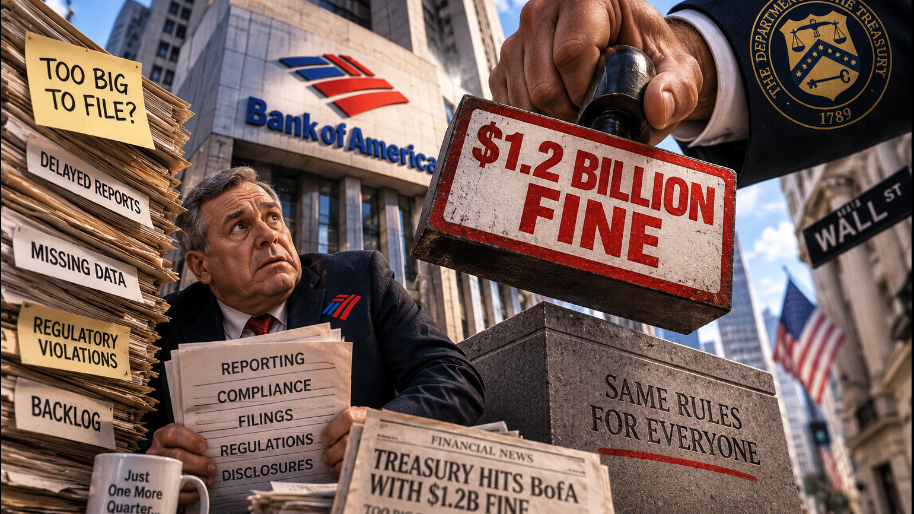
TD Bank be like: “First time?”
Uncle Sam just went scorched earth on the only bank that gets to bear the name of this great nation (read: Bank of America $BAC) after it got its TD Bank on.
On Tuesday, Treasury hit the nation’s second-largest bank with more than $1.2B in penalties after it failed, for years, to report more than $5B in suspicious transactions. More than $1B of that involved national security risks, including Chinese money-laundering networks and activity tied to the southwest border (WeBull, that you?). Additionally, red flags tied to possible narcotics proceeds and fraud also sat around unaddressed. This is day one stuff, you guys…
Oh, and BofA admitted it willfully violated the Bank Secrecy Act, the law that makes banks report shady money to the feds. Which, bold.
For context, the OCC chipped in a $750M penalty (counted toward the $1.2B), the biggest it has ever handed out. FinCEN says the total is the third-largest in Treasury history, behind Binance and TD Bank. Treasury also tacked on a separate $11.6M settlement over sanctions violations.
Per Treasury, the bank “prioritized its revenues” and leaned so hard on tips from law enforcement and other banks that it basically outsourced its suspicious-activity detection. Meaning, instead of snitching on reporting its own customers, BofA mostly waited for the cops to call. It even signed a 2024 cease-and-desist order promising to fix exactly this, and didn’t. FAFO, BofA.
Comptroller Jonathan Gould called the violations “egregious and continued.” Friendly reminder, when Trump accused Brian “Responsible Growth” Moynihan of debanking conservatives at Davos last year, the CEO’s defense was “We bank everybody.” Apparently, he wasn’t kidding.
As for Brian, the guy spent his first few years in charge cleaning up Countrywide’s f*ck up of epic proportions, then the next decade preaching his favorite catchphrase. In February, the board handed him a $41M pay package, citing “disciplined expense management.” Turns out, compliance was the expense.
The bank says it’s “far along” in remediation (congrats, when’s the due date?) and will eat a $1.2B non-tax-deductible charge in Wednesday morning’s Q3 results, about 17 cents a share, to make everyone forget all this happened. Of course, no one is going to forget all this ever happened. You see, the bank also has to pay for a third-party lookback and independent reviews until the government decides it’s gotten its sh*t together. Shares fell ~2% after hours.
“Ashtray money, bro.” - Brian Moynihan, probably
Scotty B. (read: Treasury Secretary Scott Bessent) says the penalties send “a clear message that even the biggest financial institutions are not above the law.” Just don’t expect anyone to see the inside of Club Fed. Even CZ only did four months before his pardon.
Point is, “responsible growth” means the same thing it meant in high school: pull out and pray.
Until next time, friends…
At the time of publishing, Stocks.News does not hold positions in companies mentioned in the article.
Did you find this insightful?
Bad
Just Okay
Amazing
Disclaimer: Information provided is for informational purposes only, not investment advice. We do not recommend buying or selling stocks. Stock price discussions are based on publicly available data. Readers should conduct their own research or consult a financial advisor before investing. Owners of this site have current positions in stocks mentioned throughout the site, Please Read Full Disclaimer for details Here https://app.stocks.news/page/disclaimer