


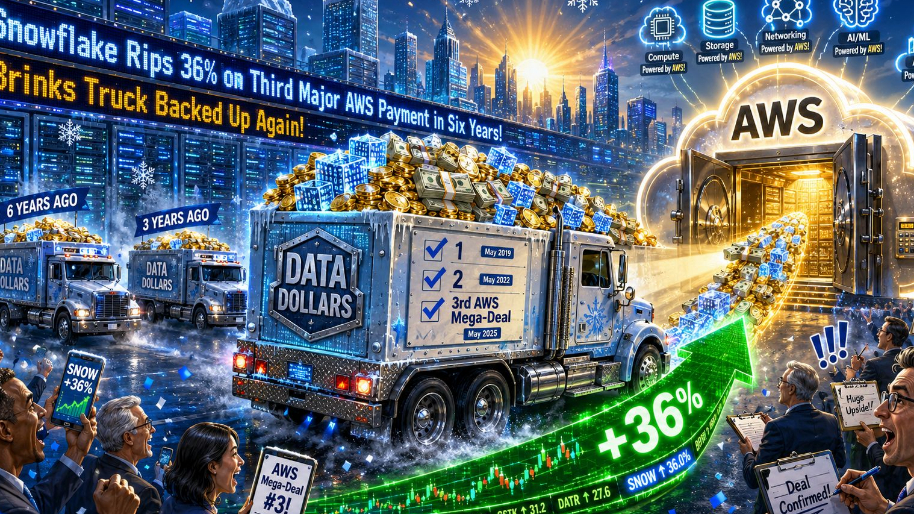
Live look at Snowflake joining the Anthropic and OpenAI in the hyperscaler hostage group chat…

Snowflake just committed five years of forward cash flow to its single biggest vendor and the stock went sicko mode anyway. Q1 adjusted EPS landed at 39 cents on $1.39 billion in revenue, up 33% year-over-year, both above the 32-cent and $1.32B Street consensus. Q2 guidance came in at $1.415 to $1.420 billion in product revenue against the $1.37 billion analysts expected, with a 12.5% margin versus the 11.9% looked for. Snowflake also bagged AI startup Natoma for an undisclosed sum. Shares popped as much as 36% in extended trading because beating numbers is how you keep the lights on at a $60 billion mid-cap that's been pricing in this exact moment for two quarters.
Then, Amazon happened. Snowflake committed $6 billion over five years to AWS, including Graviton CPUs, cloud GPUs, and whatever else is on the menu. That works out to $1.2 billion a year on average. For context: Snowflake's amended 2020 IPO cloud commitment was $1.2 billion total over five years. The 2023 update bumped it to $2.5 billion. Three years later, the new number is six. The trajectory is inspiring.
What’s interesting is what this deal does not include. For instance, when Anthropic dropped its $100 billion AWS commitment in April, AWS took an equity stake in Anthropic. Same model for the OpenAI deal: equity flows one way, compute money flows the other. Snowflake's $6 billion deal includes no equity at all. Translation: AWS is investing in the AI labs whose dependence on its cloud they can't operate without, and just billing the public-company customers who already had nowhere else to go.
Meanwhile, Andy Jassy spent his April earnings call noting that Meta is running "hundreds of thousands" of Graviton chips for its agentic AI buildout. Stack the $100 billion Anthropic pledge, the OpenAI deal, the Meta fleet, and now Snowflake's $6B, and AWS is locking down the AI cloud market in the most aggressive multi-front grift grab since the streaming wars. Bigly.
Which makes the chip war the casualty. Server CPUs lived on x86 for fifty years, the architecture Intel pioneered in the 1970s and AMD muscled into a couple of decades later. Apple kicked off Arm in mobile in 2007. AWS dragged Arm into the data center with Graviton in 2018. Now every hyperscaler runs custom Arm-based silicon, Meta is on hundreds of thousands of Graviton chips, and the x86 incumbents are watching the most profitable corner of the server market migrate to architecture they don't make. Intel got cucked on PC chips, then on mobile, then on AI accelerators. The CPU was supposed to be the safe pocket. Whoops.
So yeah… yesterday was the official day a data warehouse company tripled down on the one vendor it can't replace and the market handed it a 36% applause for the conviction. Wall Street stays undefeated. Until next time, friends…
At the time of publishing, Stocks.News holds positions in Apple, Intel, Meta, and Amazon as mentioned in the article.
Did you find this insightful?
Bad
Just Okay
Amazing
Disclaimer: Information provided is for informational purposes only, not investment advice. We do not recommend buying or selling stocks. Stock price discussions are based on publicly available data. Readers should conduct their own research or consult a financial advisor before investing. Owners of this site have current positions in stocks mentioned throughout the site, Please Read Full Disclaimer for details Here https://app.stocks.news/page/disclaimer