


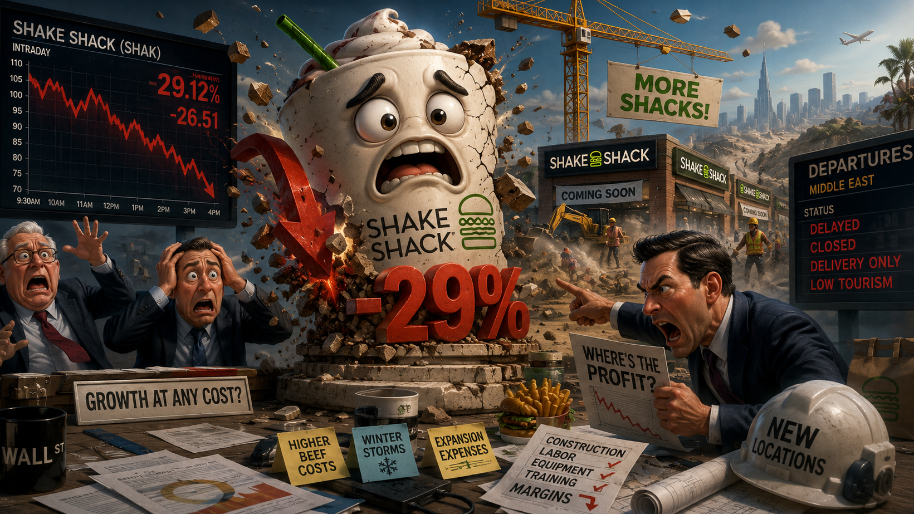
Shake Shack shares got absolutely smoked Thursday, falling nearly 30% after the burger chain reported quarterly results that reminded Wall Street of one simple fact: opening a ton of new burger locations gets expensive fast.
The NYC-based burger company posted an operating loss of $2.6 million during the quarter, while revenue came in at $367 million, below analyst expectations of $372 million. Earnings per share also missed by a pretty decent margin, landing at break-even versus analyst estimates calling for $0.12.
And honestly, this wasn’t just some “one bad quarter” situation where investors lost their minds for no reason. There were a few things working against the company all at once.
According to CEO Rob Lynch, winter storms and rising beef costs hurt profitability, while the company’s push to open more locations added additional pressure to expenses. Just goes to show that while growth is still happening, it's not coming cheap.
The company now expects to open even more stores this year than originally planned, which sounds great in theory… until you realize every new location comes with construction costs, labor, equipment, training, and all the other fun stuff that eats margins alive.
And by the way, investors seem far less patient with that strategy than they were a couple years ago.
For a while, Wall Street rewarded restaurant chains for opening locations at warp speed regardless of what happened to profitability in the short term. But now? Investors want proof the math actually works. That’s where things got uncomfortable Thursday.
That said, Shake Shack kept its full-year revenue forecast of $1.6 billion to $1.7 billion intact, but widened its EBITDA outlook to a range of $230 million to $245 million. In other words: management still sees growth ahead, but the path there is looking a little messier than expected.
Then there’s the international side of this story.
The company also said the conflict in the Middle East has disrupted operations at several licensed locations across the region, with some restaurants temporarily closing or operating on a delivery-only basis. But the bigger issue financially may be that tourism traffic has slowed considerably.
That’s a problem because a lot of those high-traffic international locations tend to perform best when travelers are constantly flowing through them. When tourism cools off, sales can come down pretty quickly too.
Meanwhile, back in the U.S., consumers are still spending money on restaurants… they’re just becoming a lot pickier about where they spend it.
Fast food chains are leaning harder into value meals. Casual dining chains are running promotions nonstop. Everybody’s fighting for the same consumer dollars right now, and premium burger prices start attracting a lot more scrutiny.
None of this means Shake Shack is suddenly broken. The company is still growing. It’s still opening stores. It still has one of the stronger brands in fast casual dining. If you’ve ever eaten there, you know the food is amazing.
But after Thursday’s results, investors made it pretty clear they’re looking for profitability alongside all that expansion.
At the time of publishing this article, Stocks.News doesn’t hold positions in companies mentioned in the article.
Did you find this insightful?
Bad
Just Okay
Amazing
Disclaimer: Information provided is for informational purposes only, not investment advice. We do not recommend buying or selling stocks. Stock price discussions are based on publicly available data. Readers should conduct their own research or consult a financial advisor before investing. Owners of this site have current positions in stocks mentioned throughout the site, Please Read Full Disclaimer for details Here https://app.stocks.news/page/disclaimer