


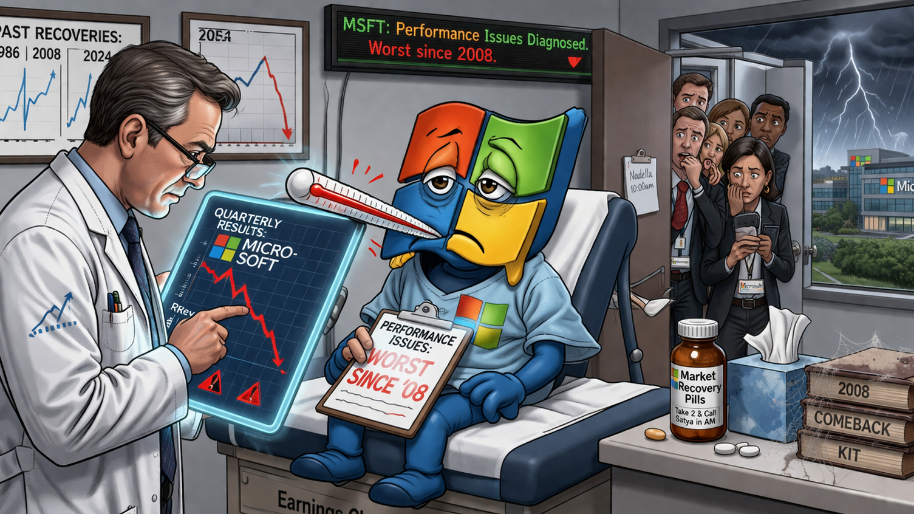
Define “down bad”...
“Doesn’t really work”. Those are Satya Nadella’s words on his own product… the one Microsoft is pouring $146 billion into this year. And so far this year, the stock agrees.
In short, the $30-a-month AI assistant that Microsoft full-sent $146 billion into this year has converted only 3.3% of users. Its US market share cratered 39% in six months. Oh, and the stonk is down 25% this quarter… worst since '08. Woof. For more context, out of all the Mag 7, Micro-soft is no doubt the biggest loser by a country mile as the rest of the group is only down -14%. Not great, but definitely not as kneecapped as the Father of Clippy.
So what’s the deal? Other than Copilot being called an “idiot genius” by those who use it, Azure revenue is shatting the bed (40 to 39 to a guided 37-38 next quarter) due to adoption headwinds. For this reason, Nadella has had to reorganize the entire division and personally sit in weekly engineer meetings debugging the thing. Translation: I definitely didn’t have the CEO of a $2.7 trillion company doing QA on my 2026 bingo card. (I'm sure that inspires confidence.)
Friendly reminder, Microsoft poured $13 billion into OpenAI Scam Altman’s pockets. And when it came time to build its most ambitious AI product… Copilot Cowork… they built it on Anthropic's tech. Because of course. Meaning the company that’s quite literally eating Microsoft (and others) lunch got hired by Microsoft to cook it. In other words, Nadella got his Tim Cook on (read: Siri -> Gemini) because if you can’t beat ‘em, join ‘em.
As for the capex itself, Microsoft marked down $37.5 billion last quarter. $146 billion for the year. $170 billion next year. And $191 billion the year after… all while the company is sitting on $80 billion in unfulfilled Azure orders because they can't find enough electricity to run the servers.
But, but, but… here’s the silver lining (if you can call it that)...
Because Wall Street is gonna Wall Street, 63 out of 67 analysts still rate it a buy with an average price target of $592. For those just catching up here, that implies 64% upside from current levels… the highest implied return on record going back to 2009. Additionally, the stonk is trading under 20x forward earnings for the first time since 2016 while being cheaper than the S&P 500, which hasn't happened since 2015. So either this is the buying opportunity of a lifetime, or 63 analysts are about to see what “F’around and find out” actually means.
Either way, Wall Street is still hot and bothered while Satya has less kind words for his work. Meaning, keep your eyes on this story and please… place your bets accordingly. Until next time, friends…
At the time of publishing, Stocks.News holds positions in Microsoft as mentioned in the article.
Did you find this insightful?
Bad
Just Okay
Amazing
Disclaimer: Information provided is for informational purposes only, not investment advice. We do not recommend buying or selling stocks. Stock price discussions are based on publicly available data. Readers should conduct their own research or consult a financial advisor before investing. Owners of this site have current positions in stocks mentioned throughout the site, Please Read Full Disclaimer for details Here https://app.stocks.news/page/disclaimer