


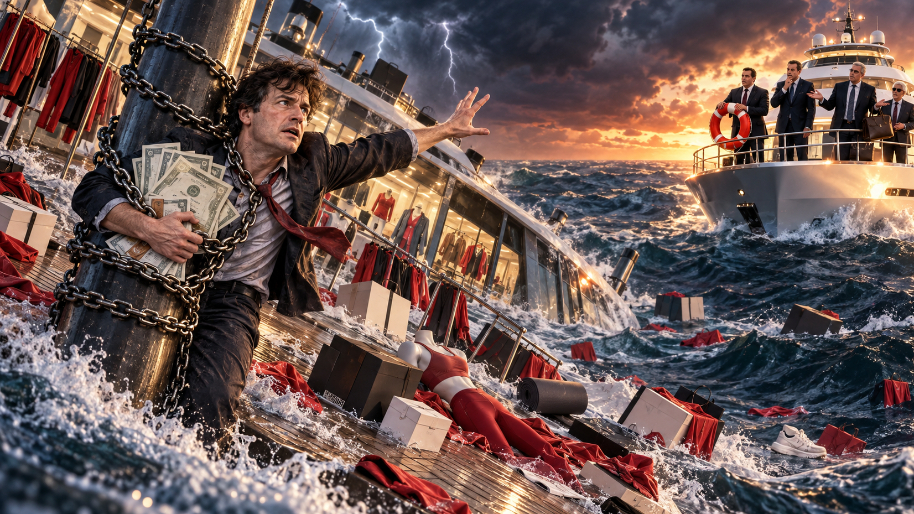
Lululemon CEO: Please. Just give us one bullish investor.
Universe: Best I can do is Michael Burry.
We might need the great Sherlock Holmes to come out of retirement and investigate Burry’s portfolio… because I refuse to believe this guy is actually this bad at investing.
The man shorted Nvidia and Palantir, called the whole thing a “circle jerk economy” (which, fair), and watched both companies continue printing unbelievable earnings… only to double down on a holding even my wife could tell you is a screaming SELL.
In case you’re not following, I’m talking about the one thing scarier than the housing market in 2008…
A pair of $118 leggings nobody wants anymore.
The Big Short legend watched his largest position, Lululemon, get sent to live with fellow pandemic legends Nike and Peloton Friday after another quarter of fashion crimes sent shares crashing 17.4%.
And somehow, Burry is still buying.
“Today, lululemon is the trickster in my portfolio,” Burry wrote on Substack. “This time the trickster is my largest position, and it does seem determined to take me where mermaids fear to tread.”
Translation: I’ve come too far to start making rational decisions now.
“Okay, enough bullying the one-eyed drummer boy… the man has clearly lost his remaining marble.” -you feeling sorry for the guy
Unfortunately, we haven’t reached the concerning part yet.
Burry reportedly plans to load up on Lululemon below $100 while betting private equity could eventually perform mouth-to-mouth on the dying athleisure brand.
Because when your biggest holding damps nearly 20%, the only responsible response is apparently to back the Burry family dump truck directly into the wreckage.
Live footage of Burry’s kids watching Dad piss away their future trust funds.
To play devil’s advocate, Burry has made an entire career out of looking like a complete f***ing idiot right before everyone else does. He reminded readers that he bought Avanti at $12, rode it into the $2 gutter, kept buying, and eventually cashed out when the company was acquired for $22 per share.
That thesis would hold way more weight if the man’s best-performing portfolio weren’t his Twitter block list.
I mean, if you look at the numbers, this pandemic legend is dangerously close to a “Where Are They Now?” special.
Revenue dropped 4% to $2.42 billion last quarter, comparable sales sank 9%, revenue in the Americas fell 8%, and sales of the company’s signature leggings reportedly collapsed 20%.
Management also butchered its full-year outlook, cutting expected revenue to between $10.35 billion and $10.50 billion from its previous forecast of $11 billion to $11.15 billion.
But don’t worry… the problems are extremely fixable if you ignore the merchandising, product strategy, competition, collapsing demand, executive transition, and international brand crisis.
Speaking of finding fresh ways to embarrass shareholders, China was an especially elegant disaster.
Revenue there rose 4% on a reported basis but fell 2% when currency fluctuations were removed, badly missing Lululemon’s expectations.
Keeping with management’s “anyone but us” turnaround plan, executives blamed Chinese media, social-media backlash, and weaker traffic following a company event at the Great Wall.
Turns out, Lululemon used a Japanese-style taiko drum instead of a traditional Chinese drum… which went over about as well as wearing a MAGA hat to an AOC rally.
Tmall also declined to repeat the same promotion it ran during last year’s 618 Shopping Festival, adding another headwind for online sales.
China’s fault. TikTok’s fault. The drums’ fault. Definitely not the $118 see-through pants.
Meanwhile, analysts have been throwing their Buy ratings overboard, and market commentator Nicholas Mugalli noted that Lululemon remains a crowded short and one of the worst-performing names in sportswear this year.
Gary Black of The Future Fund called the collapse predictable, blaming “poor merchandising, product strategy, and leadership.” He also criticized the four-month gap between Lululemon announcing incoming CEO Heidi O’Neill in April and her official arrival on September 8.
Nothing says “urgent turnaround” quite like putting the new captain on a four-month layover while the ship fills with water.
Now O’Neill inherits shrinking sales, stale products, angry Chinese consumers, Alo Yoga and Vuori stealing customers, and the sad reality of Michael Burry being your biggest believer (which is worse than the Cramer curse right now).
Just another reminder that just because you were right once, doesn’t mean you’re a genius contrarian. Sometimes the best move is to just buy Nvidia.
At the time of publishing this article, Stocks.News doesn’t hold positions in companies mentioned in the article.
Did you find this insightful?
Bad
Just Okay
Amazing
Disclaimer: Information provided is for informational purposes only, not investment advice. We do not recommend buying or selling stocks. Stock price discussions are based on publicly available data. Readers should conduct their own research or consult a financial advisor before investing. Owners of this site have current positions in stocks mentioned throughout the site, Please Read Full Disclaimer for details Here https://app.stocks.news/page/disclaimer