


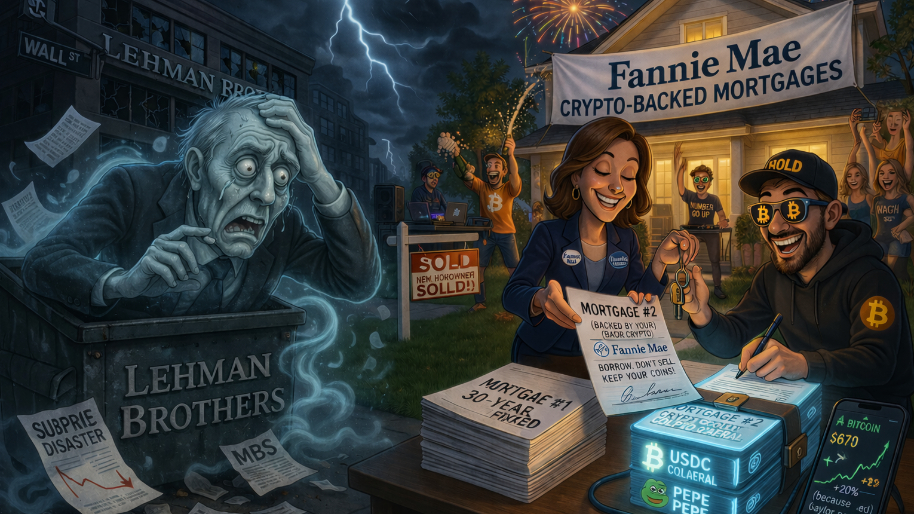
Fannie Mae: “We’ve learned our lesson from what happened in 2008. We should’ve all known something bad was coming when strippers started coming into the office introducing themselves as real estate investors.”
Also Fannie Mae: “Now instead of a normal cash down payment, would you like to take out a second loan backed by your Pepe holdings?
In case you’re wondering how desperate the real estate market is to move inventory… Fannie Mae just became the first mortgage company in history to green light crypto-backed mortgages. Somewhere, Lehman Brothers’ ghost is nodding like a proud parent.
Here’s the pitch:
Instead of selling your crypto to make a down payment (boring, responsible, IRS-approved behavior), you can now borrow against it.
So your home purchase stack looks like this:
-Mortgage #1 -> normal 15- or 30-year loan
-Mortgage #2 -> backed by your crypto or USDC stash
Translation: you don’t have to sell your crypto… you just strap a second loan to it like a financial sidecar and pray both markets behave.
Now, the dream they’re selling is pretty obvious. Crypto bros sitting on paper gains don’t want to trigger capital gains taxes… or worse, miss the next Bitcoin run to $100k (or $1 million if you ask Cathie Wood).
So instead, they get to keep their coins… and still buy a house.
According to Max Branzburg at Coinbase… the issue isn’t that people don’t have money… it’s that their net worth is sitting in crypto instead of cash.
And now the system is finally saying, “Fine. We’ll pretend that’s normal.”
But here’s where everything starts to look financially questionable… That second loan? Like anything in life, it’s not free.
Interest rates can run up to 1.5% higher, meaning you’re paying extra for the privilege of not selling your crypto.
So instead of selling Bitcoin and putting cash down.
You’re paying interest… on a loan… backed by an asset that swings 20% because Michael Saylor tweeted an AI image of himself surfing on a Bitcoin board. And before you ask… No, you can’t trade the crypto once it’s pledged.
Now on the flipside, some would argue this isn’t completely insane. Crypto ownership is climbing (about 14% of U.S. adults held it in 2025) and nearly 13% of younger buyers already sold crypto to fund down payments. So the demand is real. Others would say this is Wall Street clambering at the bit to take a trend and leverage the heck out of it.
It’s also worth noting the Federal Housing Finance Agency has been nudging this along, telling Fannie and Freddie Mac to start treating crypto like a real asset for years now.
But let’s not kid ourselves here… crypto is still wildly volatile. We’re talking about an asset that’s dropped 40%+ from recent highs. And now it’s helping secure 30-year debt obligations.
The way I see it… it’s kind of a win-win either way.
If this actually works, a whole wave of first-time buyers finally gets a shot at owning a home… something that’s felt borderline impossible for years.
If it goes badly, well, at least we’ll get a sequel to the Big Short movie.
At the time of publishing this article, Stocks.News holds positions in Bitcoin and Ethereum as mentioned in the article.
Did you find this insightful?
Bad
Just Okay
Amazing
Disclaimer: Information provided is for informational purposes only, not investment advice. We do not recommend buying or selling stocks. Stock price discussions are based on publicly available data. Readers should conduct their own research or consult a financial advisor before investing. Owners of this site have current positions in stocks mentioned throughout the site, Please Read Full Disclaimer for details Here https://app.stocks.news/page/disclaimer