


Fair Isaac UnFair Isaac
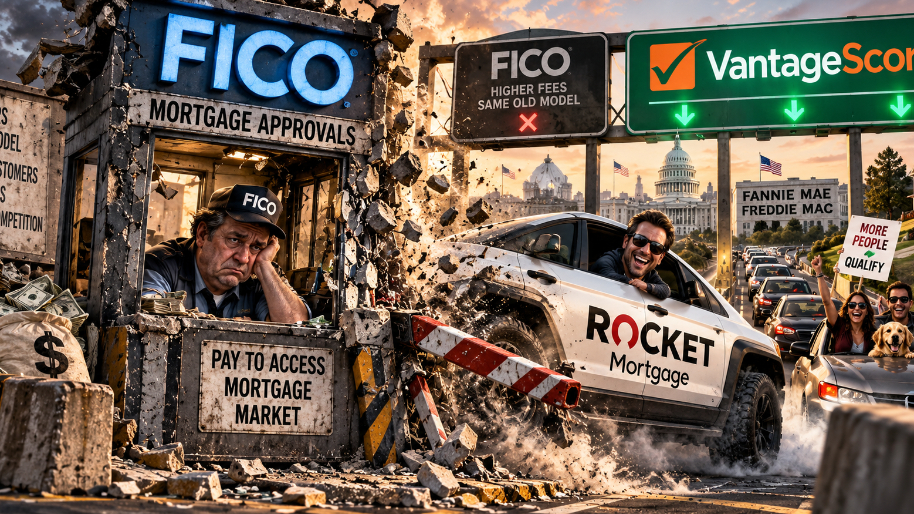
For more than 30 years, Fair Isaac has enjoyed one of the sexiest arrangements in American finance: if a mortgage lender wanted to sell your loan to Fannie Mae or Freddie Mac, Classic FICO was essentially the required credit-scoring standard.
Meaning lenders didn’t exactly choose FICO.
They chose FICO in the same way you “choose” to remove your belt at TSA.
Now cough up the money and keep the line moving.
Needless to say, being the government-sponsored mortgage industry’s favorite three-digit hall monitor turned out to be a pretty lucrative gig.
Every time some poor bastard wanted to buy a three-bedroom ranch with gray LVP flooring and a Live Laugh Love sign in the kitchen, FICO was standing at the tollbooth with its hand out.
But after three decades of Fair Isaac deciding who gets the house and who gets another year in mom’s basement…
Washington has apparently decided Fair Isaac has been a little too UnFair Isaac.
Shares jumped off a cliff, opening down 20% after FHFA Director Bill Pulte (yes, that Pulte, grandson of the guy who founded Pulte Homes) announced Fannie Mae and Freddie Mac are moving toward one mortgage pricing grid, with competing credit model VantageScore 4.0 sitting alongside Classic FICO.
“Wait, there’s another guy?” -every mortgage borrower since 1995
Normally, the words “mortgage pricing grid” would cause me to fake my own death just to escape the conversation.
This one matters.
Because the pricing grid helps determine the upfront fees Fannie and Freddie charge lenders based partly on a borrower’s creditworthiness.
And putting VantageScore inside the same framework makes it considerably easier for lenders to originate and price eligible mortgages without paying FICO for the privilege.
In other words, Washington just gave FICO’s customers something they haven’t had in 30 years:
The ability to say “nah.”
Unfortunately, Rocket Mortgage immediately exercised its newfound constitutional right.
Because almost immediately afterward, America’s largest mortgage lender announced it will make VantageScore 4.0 its preferred scoring model for all eligible mortgages beginning in Q4.
Oh.
That’s slightly more concerning than another strongly worded letter from Washington.
Rocket spent four months testing VantageScore and says the competing model helped more borrowers qualify while reducing credit-scoring costs.
In other words: Rocket tried the store-brand FICO and discovered it didn’t taste like cardboard.
So now we’ve gone from:
“Technically, lenders are allowed to use a FICO competitor.”
To:
“The biggest mortgage lender in America would actually prefer to use the FICO competitor.”
So pour a cold one out for three decades of financially judging everyone else.
Your turn, bitch.
Grok, lower FICO’s credit limit.
At the time of publishing this article, Stocks.News doesn’t hold positions in companies mentioned in the article.
Did you find this insightful?
Bad
Just Okay
Amazing
Disclaimer: Information provided is for informational purposes only, not investment advice. We do not recommend buying or selling stocks. Stock price discussions are based on publicly available data. Readers should conduct their own research or consult a financial advisor before investing. Owners of this site have current positions in stocks mentioned throughout the site, Please Read Full Disclaimer for details Here https://app.stocks.news/page/disclaimer