


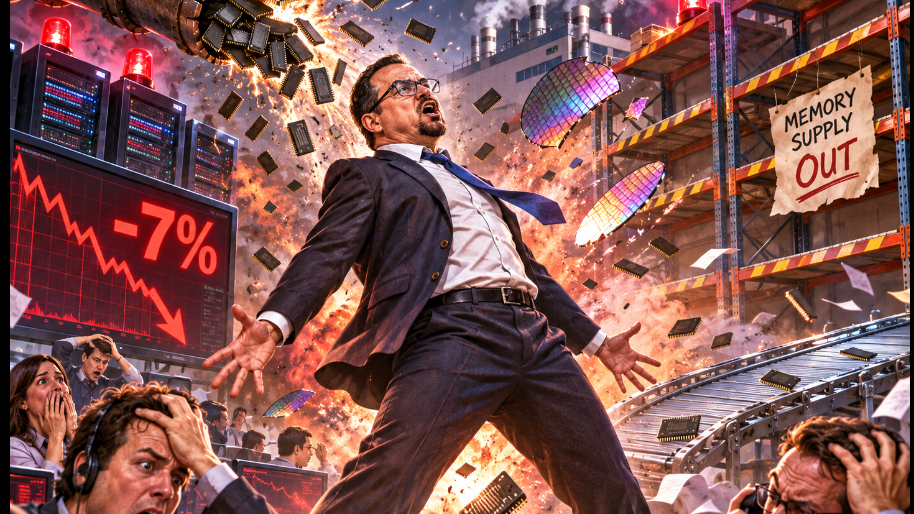
Define, “suffering from success”...
Well, life comes at you fast, friends. Just ask Qualcomm. The company best known for its phone chips (which, about that…) topped estimates Wednesday ($2.17 in adjusted EPS vs. $2.16 expected, on $10.44B in revenue). So shares obviously slid 7% after hours…
To be fair, the stock was up 5% during trading after Qualcomm announced a deal with SpaceX. Then came the guidance. The Q expects earnings of $2.15 to $2.35 per share this quarter, vs. the $2.27 the Street was looking for. Meaning, the midpoint misses by two cents (revenue guidance was actually fine). Still a tough crowd.
It’s just that the phone business is a Grade A sh*tshow. Handset chip sales face-planted 26% to $5.14B (vs. $5.21B expected), and phones are still about half of Qualcomm’s revenue. You see, AI data centers have the world’s memory chips in a chokehold. That’s jacking up memory costs, and phone makers are passing the bill on to the poors (read: you and me), who are buying fewer phones. Total revenue fell 7% YoY, too.
Per Temu Ronaldo (read: CEO Cristiano Amon) back in July: “Cost went up, prices are going to go up.” Sure enough, Qualcomm raised its own chip prices in September, right into the slump. Which, bold strategy, Cotton. Qualcomm says Android shipments in China have bottomed, but it still expects the phone market to be flat in 2027. Woof.
“But, what about the car chips?” - you a savvy investor who reads Stocks.News…
Glad you asked. Car chips, on the other hand, had themselves a day. Revenue grew a girthy 89% to $1.99B (vs. $1.66B expected), and IoT (think: smart glasses and laptop chips) rose 4% to $1.88B. That SpaceX deal has Qualcomm supplying tech for Starlink’s cellular buildout. Licensing revenue slipped to $1.3B (in line with estimates), even after Qualcomm renewed deals with Huawei, Transsion, and Apple (which has been trying to pull out for years… see: its own modems).
As for data centers, it’s been a helluva year since the Q stepped into the sauna with Nvidia and AMD (and removed its towel). The stock popped 15% in June when Qualcomm nearly doubled its 2029 target for not-phone revenue, then fell off a cliff (think: down nearly 40% from its 52-week high). Qualcomm booked $650M in data center revenue this quarter, mostly custom chip and connectivity work, and Cristiano expects $5B in fiscal 2027. He says it just signed an optical connectivity customer and has a sneaky link with an unnamed global hyperscaler.
The catch though, per Cristiano, is that there isn’t enough supply to go around: “If I had more supply, I would probably be doing better.” And if my grandmother had wheels, she’d be a bike.
So, same reaction investors had back in 2024, when the Q first pitched Wall Street on life after phones… “Cool story, bro.” Place your bets accordingly, friends. Until next time…
At the time of publishing, Stocks.News holds positions in Apple as mentioned in the article.
Did you find this insightful?
Bad
Just Okay
Amazing
Disclaimer: Information provided is for informational purposes only, not investment advice. We do not recommend buying or selling stocks. Stock price discussions are based on publicly available data. Readers should conduct their own research or consult a financial advisor before investing. Owners of this site have current positions in stocks mentioned throughout the site, Please Read Full Disclaimer for details Here https://app.stocks.news/page/disclaimer