


Annnnd it’s gone (read: AI’s credit limit)…
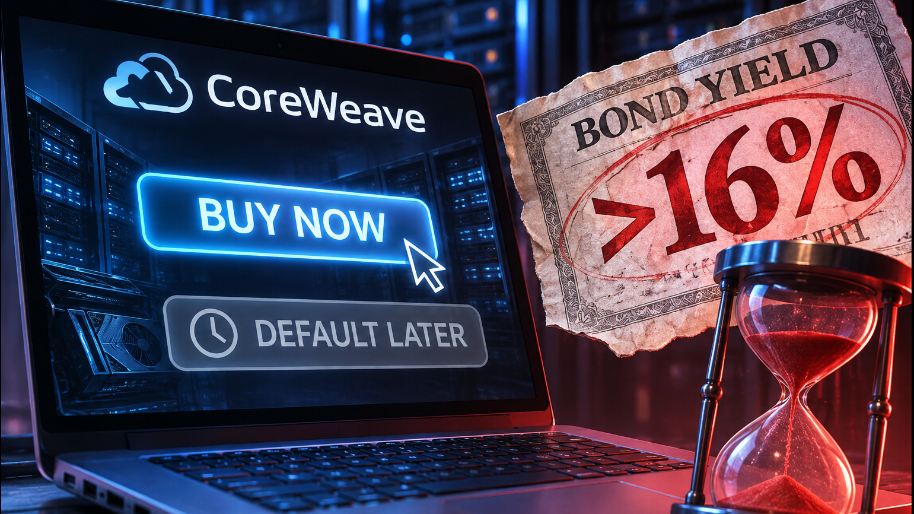
The only thing more American than financing a 2015 Chevy Silverado for 204 months at 19.25% APY might be financing a warehouse full of Nvidia chips at 16%.
Say hello to The CW (read: CoreWeave), the proud owner of sh*t loads of GPUs it rents out to Big Tech. The yield on its 9.625% bonds due 2032 just blew past 16% (read: what lenders now want to touch this thing). Its five-year credit default swaps (think: insurance in case CoreWeave stiffs them) spiked above 1,289 bips on Thursday, past their October peak, before easing to around 1,155 on Friday. Meaning, it costs about $1.16M a year to insure $10M of its debt.
Translation: debt markets are hiking the rate on AI’s credit card. Per Jefferies’ Christopher Wood (no relation to Cathie), “the most plausible way the AI capex arms race will end is that the credit card will be taken away.” Apparently, the folks over at Jefferies have been listening to a little too much Dave Ramsey…
Now, nobody’s cut up the card just yet. But lenders got spooked on Tuesday, when Democrats took Congress and key governors’ mansions. Where’s Donny’s 10% cap on card rates when you need it? Voters also rejected data centers in 40 of 41 local ballot measures (because hell hath no fury like a group of PTA moms with a Facebook group).
Even the big swingin’ balance sheets need insurance now. CDS on Nvidia is up 76% in a month. Broadcom, run by a guy literally named Hock Tuah, is up 49%, and the online bookstore (read: Amazon) is up 44%. To be fair, Nvidia’s only around 139 bips, vs. about 298 for Oracle and 1,155 for The CW. It’s just that Nvidia owns about 10% of CoreWeave and sold it the GPUs. That’s still the incestual clusterf*ck that is the AI ecosystem for you.
So when does all this spending actually make money? Per Goldman (yes, the Apple Card guys), hyperscalers (read: Big Tech) collectively went negative on free cash flow in Q3. The math is not mathing.
And if they pump the brakes, the neoclouds (think: GPU landlords like The CW) get bodied first with fewer and shorter contracts. Meanwhile, The CW’s sitting on a Johnny Sins-sized debt load (more than $51B in debt and obligations).
A big chunk is backed by the GPUs themselves, kinda like Rashee Rice putting up his Super Bowl ring this week. For Q3, which The CW reports Tuesday, it guided to $860M-$940M in interest vs. $200M-$260M in adjusted operating income. Per Mike Intrator, the ex-crypto miner running the joint, “scaling is expensive.” In other words, it’s about to start paying off the Visa with the Mastercard.
As for what’s next, Bank of America sees AI-related credit issuance rising 31% to a cool $685B in 2027, then falling 23% to $531B in 2028. Meaning, AI debt finishes next year, then rolls over and goes to sleep. The risk? The Blue Wave slows projects down, which means less capex.
So the doomsday scenario for AI’s debt problem is… less debt. Dave Ramsey’s been threatening us with that for 30 years. Your move, Mike…
Until next time, friends!
At the time of publishing, Stocks.News holds positions in Apple and Amazon as mentioned in the article.
Did you find this insightful?
Bad
Just Okay
Amazing
Disclaimer: Information provided is for informational purposes only, not investment advice. We do not recommend buying or selling stocks. Stock price discussions are based on publicly available data. Readers should conduct their own research or consult a financial advisor before investing. Owners of this site have current positions in stocks mentioned throughout the site, Please Read Full Disclaimer for details Here https://app.stocks.news/page/disclaimer