


Mic-ron Drop…
Well friends, the grade came back overnight, and Micron didn't just pass it. It blew the curve so hard the after-hours tape lit up 15% green, with a $50 billion next-quarter forecast stapled to the front of the exam. And all Gods tech degenerates said “Amen”.
Revenue landed at $41.46 billion against a $35.84 billion estimate, earnings at $25.11 a share, and HBM capacity already sold out through 2026. Right on cue, the entire timeline started screaming the same three words: buy the dip. BUT… while the FOMO is real af with this one, it might not be a good idea to chase it.
See, that 15% pop sounds heroic until you clock where it actually lands the stock, which is roughly $1,206, or about four bucks below where Micron closed last Monday before the AI selloff cratered it 13% in a single session. Meaning, even though some may call it a breakout… what it really is, is a guy climbing back through the same window he got thrown out of 72 hours ago and calling it a comeback.
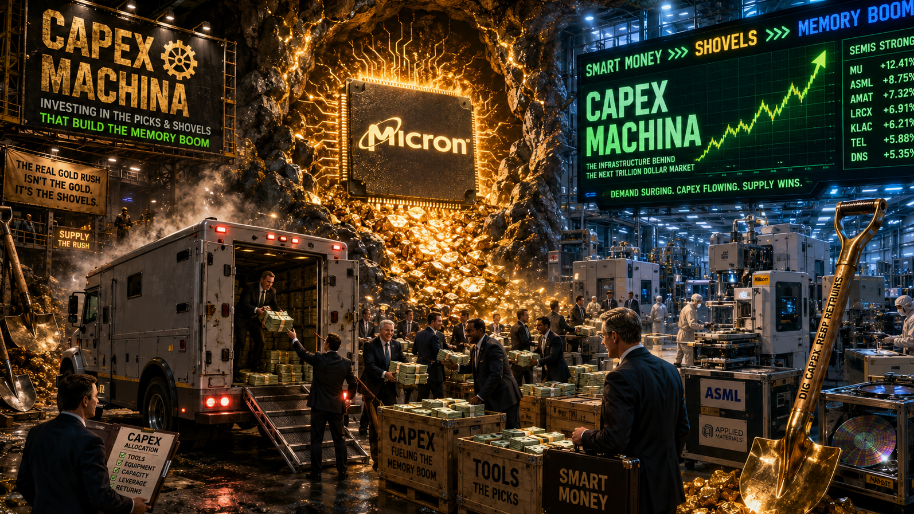
Which is why I’m more interested in the part the buy-the-dip crowd skated right past. Buried under the revenue fireworks, Micron lit the fuse on its full-year capex, booming it from $20 billion to north of $25 billion (a 25% raise in a single quarter, for the people keeping score). That extra $5 billion does not stay in Boise. It gets mainlined straight to the companies that build the machines that make the chips: Lam Research, Applied Materials, KLA, and ASML. That’s the real opportunity of this shindig. And it's the oldest one in the book: Sell the damn shovels.
Lam and Applied cash that check whether HBM pricing holds, whether the memory cycle rolls over, and whether Micron's own insiders turn out to be right. They're levered to the entire capex supercycle, Micron plus TSMC plus Samsung plus Intel (read: everyone digging), not one company's memory margins. The miner takes the cycle risk while the shovel guys already got paid. Case in point: KLA rides the same wave with a kicker, because the taller and more delicate the HBM stacking gets, the more inspection and process-control gear it has to move. And ASML, the only outfit on Earth that builds an EUV lithography machine (yes, a literal monopoly), just got a hard, public commitment from its biggest memory customer to spend $5 billion more than planned, with UBS pegging the multi-year tab north of $50 billion. In plain English… Micron's rising costs are these companies' rising revenue.
Oh, and speaking of more receipts (and insiders). Sell-jay (read: CEO Sanjay Mehrotra) dumped 40,000 shares at $511 to $545 on May 1, then another 2,561 at the end of the month. Insider buys over the past year, while the stock ran 10x off its $103 low? Zero. Translation: The trillion-dollar party in early June came with a trail of Form 4 sales, not buys, which we'll generously file under cashing out at the top while you buy the press release "diversifying under a pre-arranged plan."
So yeah… that was Microns earnings for ya. Sure, the stonk struck gold, but in reality… it’s just a headline pop that brought us back to last Monday. The savvier read here is to be over there with the shovel salesman… getting paid either way. Place your bets accordingly, friends. Until next time…
At the time of publishing, Stocks.News holds positions in Intel as mentioned in the article.
Did you find this insightful?
Bad
Just Okay
Amazing
Disclaimer: Information provided is for informational purposes only, not investment advice. We do not recommend buying or selling stocks. Stock price discussions are based on publicly available data. Readers should conduct their own research or consult a financial advisor before investing. Owners of this site have current positions in stocks mentioned throughout the site, Please Read Full Disclaimer for details Here https://app.stocks.news/page/disclaimer