


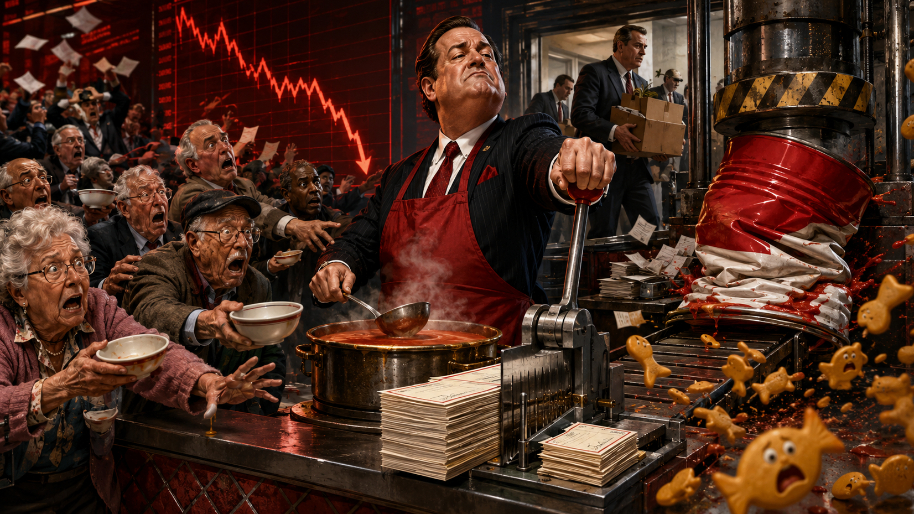
Turns out there is a real-life Soup Nazi… and his name is Mick Beekhuizen.
Campbell's CEO just cut the company’s quarterly dividend by 36%, after sales, profits, and margins all got tossed into the same industrial-sized soup blender.
No soup dividend for you!
Campbell’s shareholders bagholders woke up this morning expecting a warm bowl of fiscal stability and instead got served a 36% dividend cut with a sleeve of crushed Goldfish on the side.
Shares of Travis Kelce’s favorite Great Depression delicacy plunged 9% after the 155-year-old food company reported falling sales, shrinking margins, collapsing profits, and guidance that suggested the pantry raid is nowhere near finished.
Let’s all have a word of silence for dividend investors everywhere.
Numberswise, it truly is a famine…
Campbell’s quarterly revenue dropped 8% year over year… while adjusted earnings per share fell 37% to $0.39. The company’s GAAP gross margin was squeezed by 310 basis points to 27.3%, courtesy of inflation, supply-chain expenses, tariffs, and (unofficially) consumers realizing Aldi also sells soup for half the price.
Campbell’s also swung from a $145 million profit last year to a $69 million quarterly loss. That’s a $214 million journey from “M’m! M’m! Good!” to “Oh f*ck.”
CEO Mick Beekhuizen acknowledged that the company’s performance was “not where it needs to be.” Conveniently leaving out how he plans to save this grocery-store fossil from extinction.
But the real drive-by was reserved for Campbell’s dividend faithful.
The board approved a reduction in the quarterly payout from $0.39 to $0.25 per share… a 36% haircut meant to accelerate debt repayment. Even passive income is now getting laid off.
Oh, and probably nothing, but…
Campbell’s shares were already down 15% this year before today’s earnings instantly gave every shareholder clinical depression.
But at least I avoided that dangerous Nvidia stock.
The company’s full-year numbers didn’t exactly leave investors reaching for seconds, either. Fiscal 2026 revenue fell 5%, adjusted EPS dropped 27% to $2.17, and adjusted gross margin contracted 210 basis points to 28.5%.
Cash flow from operations still totaled $1 billion, but management has decided it would prefer to send less of that cash to shareholders and more of it toward paying down the company’s Discover Robinhood Gold card.
Things were particularly ugly inside Campbell’s snack aisle. Quarterly sales in the Snacks division (which houses Goldfish, Pepperidge Farm, and Snyder’s of Hanover) fell 12%, while snack volumes dropped 6%.
In other words: parents have begun informing their brats that the off-brand penguins taste exactly the same.
Meals & Beverages held up slightly better, with quarterly sales falling 4% and volumes increasing 3%. Brands such as Rao’s and Campbell’s broth provided some shelter as inflation-weary consumers continued cooking at home.
Unfortunately, management doesn’t expect the ass-kicking to end once pumpkin-spice season arrives.
Campbell’s expects fiscal 2027 sales to decline another 2% to 4%, adjusted EBIT to fall between 7% and 12%, and adjusted EPS to come in between $1.65 and $1.80.
To keep the wheels from coming off, Mick is putting all of Campbell’s on the debt snowball. The plan calls for $500 million in savings by fiscal 2030, plus plant closures, layoffs, higher prices (and possible management delivering DoorDash on the side).
Case in point: Campbell’s has already increased prices by 4% to 5% across about 60% of its portfolio as commodity and logistics costs continue eating into margins.
“I did that!” -JPow
To make matters worse, corn, wheat, and sugar prices all posted double-digit increases in August, leaving food manufacturers trapped between higher production costs and consumers who have reached the “put it back” stage of grocery shopping.
That’s the real problem here.
Campbell’s can raise prices, close plants, cut expenses, and launch enough efficiency programs to keep McKinsey consultants fed through 2030.
But if shoppers keep trading down (or stop buying altogether) the company can only squeeze its soup cans so hard before something else bursts.
For now, management is asking shareholders to swallow a smaller dividend today in exchange for the possibility of a healthier Campbell’s sometime around 2030.
Reason 1,834 why “dividend investing” is no different than picking up pennies in front of a steamroller.
At the time of publishing this article, Stocks.News holds positions in Robinhood as mentioned in the article.
Did you find this insightful?
Bad
Just Okay
Amazing
Disclaimer: Information provided is for informational purposes only, not investment advice. We do not recommend buying or selling stocks. Stock price discussions are based on publicly available data. Readers should conduct their own research or consult a financial advisor before investing. Owners of this site have current positions in stocks mentioned throughout the site, Please Read Full Disclaimer for details Here https://app.stocks.news/page/disclaimer